On this page ▾
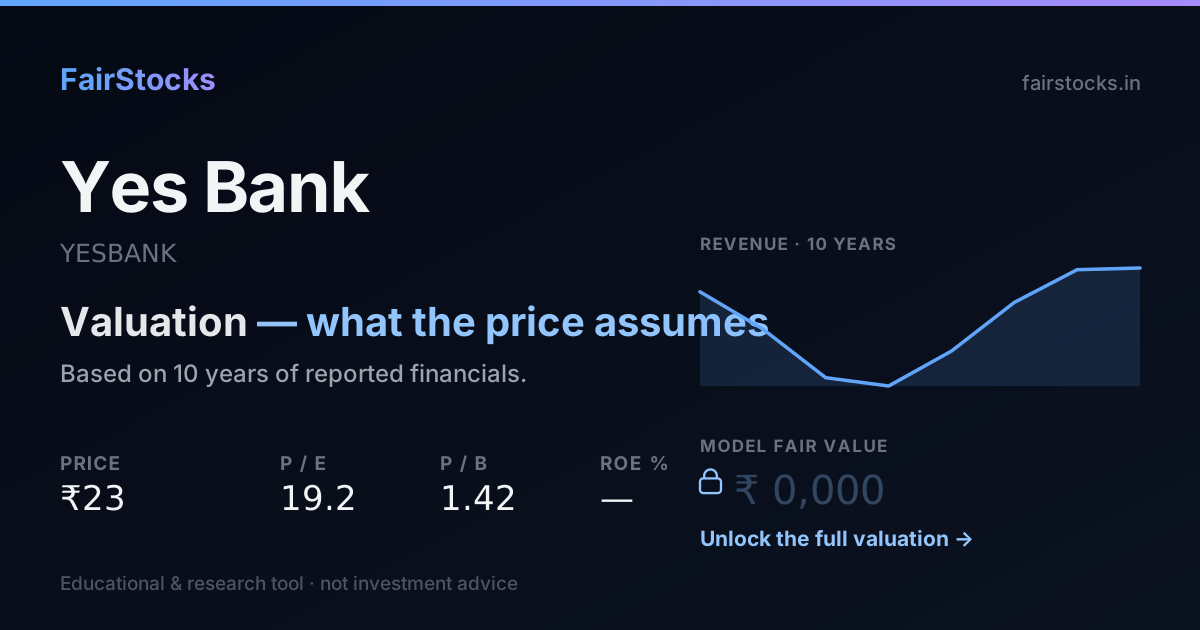
The market expects Yes Bank to do better than it ever has.
At today’s share price, buyers are assuming Yes Bank earns about 12.2% a year on the money invested in it, from here on. Over the last ten years it actually earned about 5.9% a year. So the share price only makes sense if the business improves on its own track record. If it simply carries on as before, buyers today have paid for something they will not get.
- How it is valued: Excess return — the correct lens for a bank.
- What the price assumes: 12.2% return on equity, against 5.9% the model takes from its own record.
- Ten-year record: Between FY2019 and FY2026, Yes Bank's revenue went from ₹34,299 crore to ₹37,293 crore — it barely moved over 7 years.
- Biggest swing factor: Return on equity. Main risk: Thin profitability.
01A private bank that almost failed
Yes Bank, founded in 2004 by Rana Kapoor and Ashok Kapur, grew rapidly by lending to large companies. Bad loans piled up, and in March 2020 the RBI took control and arranged a rescue led by State Bank of India.
Since then it has cleaned up its book, sold bad loans and grown retail lending. In 2025 Japan's SMBC bought a large stake to become its biggest shareholder.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the return on equity that price implies for Yes Bank, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Yes Bank's record, in plain numbers
Between FY2019 and FY2026, Yes Bank's revenue went from ₹34,299 crore to ₹37,293 crore — it barely moved over 7 years. It reported a net loss in FY2020 and FY2021, and closed the period with net profit of ₹3,512 crore. In FY2026 it kept 9.4% of revenue as net profit — its best year in the period. The latest year added 0.6% to revenue, close to its own long-run pace.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2019 | 34,299 | 1,709 | 5.0% |
| FY2020 | 29,593 | -16,433 | -55.5% |
| FY2021 | 23,475 | -3,489 | -14.9% |
| FY2022 | 22,424 | 1,064 | 4.7% |
| FY2023 | 26,827 | 736 | 2.7% |
| FY2024 | 32,961 | 1,285 | 3.9% |
| FY2025 | 37,076 | 2,447 | 6.6% |
| FY2026 | 37,293 | 3,512 | 9.4% |
04How Yes Bank gets valued — and why
Excess return — the correct lens for a bankA bank is not valued with a discounted cash flow. Deposits are its raw material and interest is operating income, so enterprise value means nothing here. It is valued on excess return instead — the profit it earns above the cost of the equity funding it.
05What decides Yes Bank's value
Return on equity
Returns are still well below large private banks.
Deposits
Rebuilding depositor trust lowers funding costs.
Retail growth
A larger retail book improves stability.
New ownership
SMBC's backing could bring capital and business.
06What could go wrong
- Thin profitability. Low returns leave little cushion.
- Legacy issues. Old loans and litigation can resurface.
- Competition. Larger banks dominate profitable segments.
07What the full Yes Bank valuation shows
Sign in free to see the complete Yes Bank valuation
- ✓Fair value per share — from the excess-return model banks are valued on
- ✓The bank workpaper — book value, cost of equity and sustainable return, step by step
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against IDFC First Bank, RBL Bank and Federal Bank
- ✓Downloadable report — the full write-up, yours to keep
08Questions people ask about Yes Bank
What happened to Yes Bank in 2020?
The RBI took control and an SBI-led group of banks rescued it.
Who owns Yes Bank now?
Japan's SMBC became its largest shareholder in 2025, alongside SBI and other banks.
Is Yes Bank profitable?
Yes, though returns remain well below larger private banks.
Is Yes Bank overvalued?
At ₹17 the market is pricing in roughly 12.2% sustained ROE, against the ~5.9% its own record supports. That is more than it has delivered, so the price is justified only if the business can hold a rate it has not previously sustained.
What is the intrinsic value of Yes Bank?
It is computed from the filed financial statements using the method that fits this business (excess return), with every assumption shown alongside the result. The per-share figure and the full working are in the report.
How much debt does Yes Bank carry?
Debt to equity stands at 1.46, down from 2.27 at the start of the period — the balance sheet is a core input to the cost of capital used here.