On this page ▾
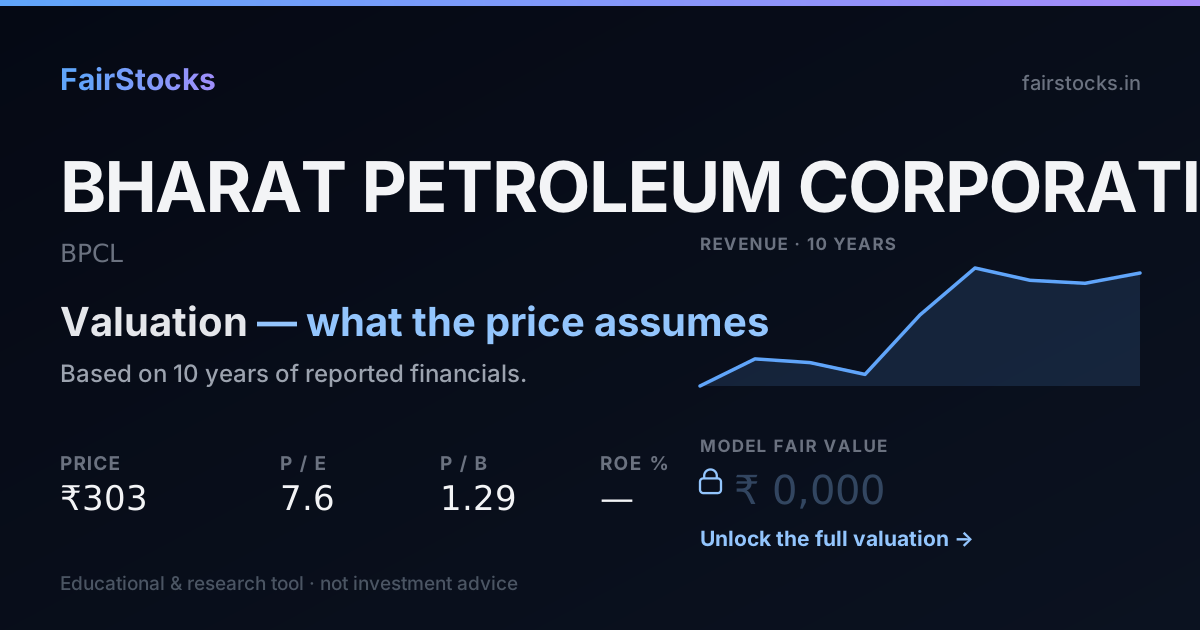
We do not publish one number for BPCL — and here is why.
On today's figures our model puts BPCL at roughly 3.2 times what the market pays for it. On a company this widely followed, a gap that large almost always means our model is missing something rather than that thousands of investors are wrong. So we show the workings and say plainly that we cannot stand behind a single figure here.
- How it is valued: no single figure is published here — our model and the market disagree too far.
- What the price assumes: 0% growth, against 3% the model takes from its own record.
- Ten-year record: Between FY2018 and FY2026, BPCL's revenue went from ₹2,79,313 crore to ₹5,22,820 crore — it compounded at about 8% a year over 8 years.
- Biggest swing factor: Refining margins. Main risk: Government pricing.
01A state refiner and fuel retailer
Bharat Petroleum Corporation (BPCL), majority-owned by the Government of India, runs refineries at Mumbai, Kochi and Bina and one of the country's largest networks of petrol pumps. It also sells LPG under the Bharatgas brand and has interests in upstream oil and gas.
The government tried to privatise BPCL by selling its majority stake but called off the sale in 2022. Like other state fuel retailers, its marketing margins depend on how far retail prices are allowed to track costs.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for BPCL, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03BPCL's record, in plain numbers
Between FY2018 and FY2026, BPCL's revenue went from ₹2,79,313 crore to ₹5,22,820 crore — it compounded at about 8% a year over 8 years. Net profit grew from ₹9,792 crore to ₹25,843 crore, about 13% a year — faster than revenue, so margins widened. In FY2026 it kept 4.9% of revenue as net profit — against a low of 0.4% in FY2023 and a high of 5.7% in FY2021. The latest year added 4.5% to revenue, well behind its own long-run pace.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2018 | 2,79,313 | 9,792 | 3.5% |
| FY2019 | 3,37,623 | 7,132 | 2.1% |
| FY2020 | 3,29,797 | 3,666 | 1.1% |
| FY2021 | 3,04,266 | 17,320 | 5.7% |
| FY2022 | 4,32,570 | 11,682 | 2.7% |
| FY2023 | 5,33,547 | 2,131 | 0.4% |
| FY2024 | 5,06,993 | 26,859 | 5.3% |
| FY2025 | 5,00,517 | 13,337 | 2.7% |
| FY2026 | 5,22,820 | 25,843 | 4.9% |
04How BPCL gets valued — and why
Estimate withheld — model and market disagree too farOur model and the market disagree so far apart on this company that the model is the more likely one to be wrong. Rather than publish a number we cannot stand behind, we show the workings and say so.
05What decides BPCL's value
Refining margins
Product prices minus crude costs drive refining profit.
Marketing margins
Retail fuel pricing decides marketing profit.
Petrochemicals
New projects add a cyclical profit stream.
Dividends
BPCL pays a large share of profit as dividends in good years.
06What could go wrong
- Government pricing. Retail prices can be held down when crude rises.
- Crude volatility. Inventory gains and losses swing reported profit.
- Energy transition. EVs will slowly reduce fuel demand.
07What the full BPCL valuation shows
Sign in free to see the complete BPCL valuation
- ✓The full model workings — and exactly where the model and the market part ways
- ✓Every assumption — growth, returns and cost of capital, with sources
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against Indian Oil, Reliance Industries and ONGC
- ✓Downloadable report — the full write-up, yours to keep
08Compare BPCL with peers
The same valuation, run side by side.
BPCL vs Indian OilTwo state refiners and marketers, head to head.→BPCL vs Reliance IndustriesPublic refining and marketing against the largest private refiner.→BPCL vs ONGCDownstream refining against upstream production.→09Questions people ask about BPCL
Was BPCL privatised?
No. The government invited bids for its stake but called off the sale in 2022.
Why does BPCL's profit swing so much?
Refining and marketing margins and inventory values move with crude prices.
BPCL or Indian Oil — which is better value?
Two state refiners and marketers, compared side by side on their own page.
Is BPCL overvalued?
At ₹302 the market is pricing in roughly 0% sustained growth, against the ~3% its own record supports. That is less than it has delivered — on these numbers the market is asking the business for less than its own record, which usually means it doubts the record repeats.
What is the intrinsic value of BPCL?
This business is a group of operations with different economics, so a single blended figure would describe none of them. The parts are valued separately and the breakdown is in the report, rather than one number that cannot be defended.
How much debt does BPCL carry?
Debt to equity stands at 0.23, down from 0.80 at the start of the period — the balance sheet is a core input to the cost of capital used here.