On this page ▾
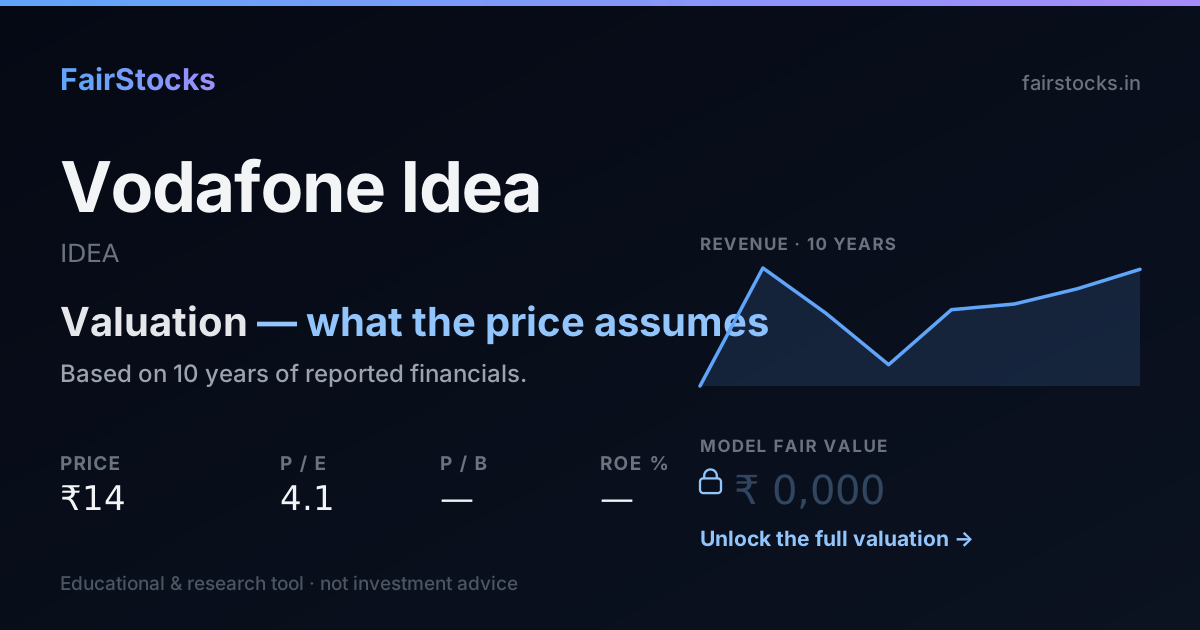
We do not publish one number for Vodafone Idea — and here is why.
Our engine has not published a single fair value for Vodafone Idea. It has made heavy losses for years, and its future depends on fresh funding and on how government dues are settled — so a figure built on its past cash flows would mean little. The workings and the record are shown instead.
- How it is valued: business by business, with no single blended figure.
- What the price assumes: 31% growth, against 2% the model takes from its own record.
- Ten-year record: Between FY2019 and FY2025, Vodafone Idea's revenue went from ₹37,092 crore to ₹43,571 crore — it compounded at about 3% a year over 6 years.
- Biggest swing factor: Funding. Main risk: Insolvency risk.
01The third operator
Vodafone Idea was formed in 2018 by merging Vodafone's and Idea Cellular's Indian businesses. It is India's third-largest mobile operator, behind Jio and Airtel, and has been losing subscribers for years.
The Supreme Court's 2019 ruling on adjusted gross revenue left it with very large dues. In 2025 the government converted part of what it owed into shares, becoming its largest shareholder, alongside the Aditya Birla group and Vodafone.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for Vodafone Idea, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Vodafone Idea's record, in plain numbers
Between FY2019 and FY2025, Vodafone Idea's revenue went from ₹37,092 crore to ₹43,571 crore — it compounded at about 3% a year over 6 years. It reported a net loss in FY2019, FY2020, FY2021, FY2022, FY2023, FY2024 and FY2025. In FY2025 it lost the equivalent of 62.8% of revenue — against a low of -164.3% in FY2020 and a high of -39.4% in FY2019. The latest year added 2.4% to revenue, close to its own long-run pace.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2019 | 37,092 | -14,604 | -39.4% |
| FY2020 | 44,958 | -73,878 | -164.3% |
| FY2021 | 41,952 | -44,233 | -105.4% |
| FY2022 | 38,516 | -28,245 | -73.3% |
| FY2023 | 42,177 | -29,301 | -69.5% |
| FY2024 | 42,555 | -31,238 | -73.4% |
| FY2025 | 43,571 | -27,383 | -62.8% |
| FY2026 | 44,873 | 34,552 | 77.0% |
04How Vodafone Idea gets valued — and why
Estimate withheld — the engine says so itselfThis is a group of businesses with different economics. A single discounted cash flow across all of them averages them into something that describes none of them, so our engine withholds a single blended fair value rather than publishing a number it cannot defend. The parts are valued separately instead.
05What decides Vodafone Idea's value
Funding
New capital is needed to expand 4G and 5G.
Government dues
How remaining dues are settled shapes survival.
Subscriber trends
Stopping subscriber losses is essential.
Tariffs
Higher industry tariffs help every operator.
06What could go wrong
- Insolvency risk. Heavy debt and dues threaten viability.
- Dilution. Further share issuance reduces existing holders' stakes.
- Competition. Jio and Airtel keep investing.
07What the full Vodafone Idea valuation shows
Sign in free to see the complete Vodafone Idea valuation
- ✓The full model workings — and exactly where the model and the market part ways
- ✓Every assumption — growth, returns and cost of capital, with sources
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against Bharti Airtel, Indus Towers and Tata Communications
- ✓Downloadable report — the full write-up, yours to keep
08Questions people ask about Vodafone Idea
Who owns Vodafone Idea?
The Government of India is the largest shareholder, alongside the Aditya Birla group and Vodafone.
Why has Vodafone Idea made losses?
Price wars, falling subscribers and large government dues.
Why doesn't FairStocks show a fair value for Vodafone Idea?
Its future depends on funding and dues settlements that past cash flows cannot capture.
Is Vodafone Idea overvalued?
At ₹13 the market is pricing in roughly 31% sustained growth, against the ~2% its own record supports. That is more than it has delivered, so the price is justified only if the business can hold a rate it has not previously sustained.
What is the intrinsic value of Vodafone Idea?
This business is a group of operations with different economics, so a single blended figure would describe none of them. The parts are valued separately and the breakdown is in the report, rather than one number that cannot be defended.