On this page ▾
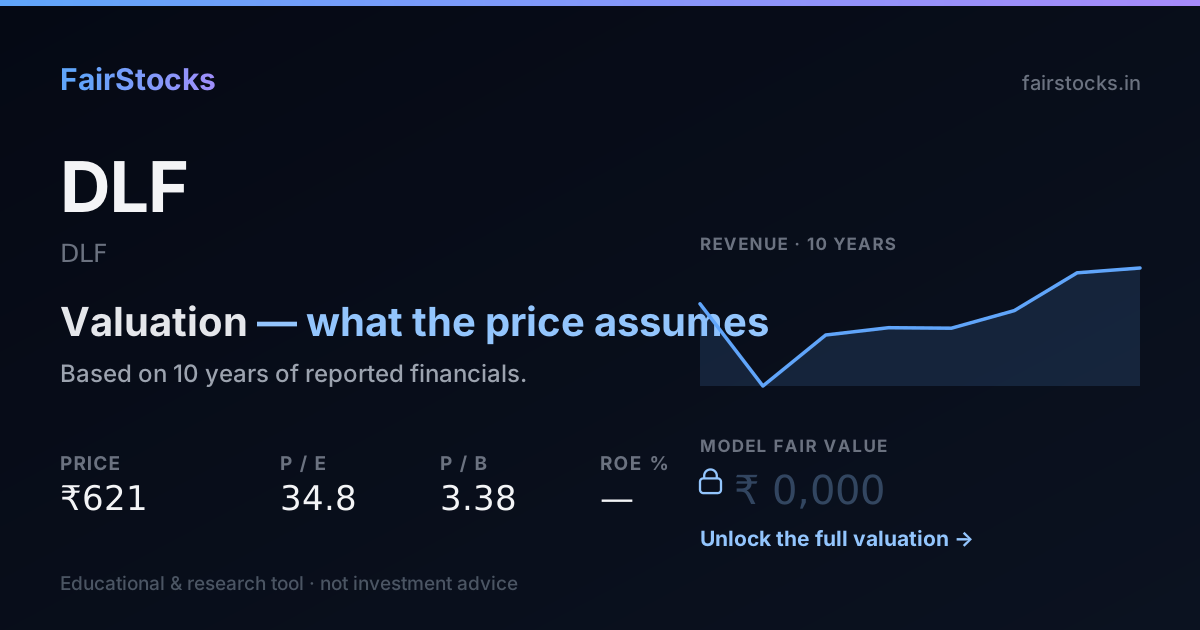
We do not publish one number for DLF — and here is why.
On today's figures the market pays roughly 3.8 times what our model says DLF is worth. On a company this widely followed, a gap that large almost always means our model is missing something rather than that thousands of investors are wrong. So we show the workings and say plainly that we cannot stand behind a single figure here.
- How it is valued: no single figure is published here — our model and the market disagree too far.
- What the price assumes: 35% growth, against 9% the model takes from its own record.
- Ten-year record: Between FY2018 and FY2026, DLF's revenue went from ₹6,707 crore to ₹8,194 crore — it compounded at about 3% a year over 8 years.
- Biggest swing factor: Launches and sales. Main risk: Property cycle.
01Gurugram's developer
DLF, founded in 1946 and controlled by the Singh family, is India's largest listed real-estate developer by market value. It largely built modern Gurugram, and its recent luxury launches such as The Camellias and The Dahlias have sold at record prices.
Its rental business, DLF Cyber City Developers, is a joint venture with Singapore's GIC that owns offices and malls such as Cyber City and Mall of India, earning steady rent. DLF still holds a large land bank in and around Gurugram.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for DLF, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03DLF's record, in plain numbers
Between FY2018 and FY2026, DLF's revenue went from ₹6,707 crore to ₹8,194 crore — it compounded at about 3% a year over 8 years. Net profit was flat at around ₹4,415 crore — slower than revenue, so margins narrowed. In FY2026 it kept 53.9% of revenue as net profit — against a low of 20.0% in FY2021 and a high of 66.8% in FY2018. The latest year added 2.5% to revenue, close to its own long-run pace. FY2020 is missing from the filed series used here, so that year is left out rather than estimated.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2018 | 6,707 | 4,477 | 66.8% |
| FY2019 | 3,295 | 688 | 20.9% |
| FY2021 | 5,414 | 1,083 | 20.0% |
| FY2022 | 5,717 | 1,500 | 26.2% |
| FY2023 | 5,695 | 2,034 | 35.7% |
| FY2024 | 6,427 | 2,724 | 42.4% |
| FY2025 | 7,994 | 4,367 | 54.6% |
| FY2026 | 8,194 | 4,415 | 53.9% |
04How DLF gets valued — and why
Estimate withheld — model and market disagree too farOur model and the market disagree so far apart on this company that the model is the more likely one to be wrong. Rather than publish a number we cannot stand behind, we show the workings and say so.
05What decides DLF's value
Launches and sales
New luxury projects drive bookings and cash flow.
Land bank
Owned land lets DLF launch without paying today's land prices.
Rental income
Offices and malls give steady, growing cash.
Pricing
Luxury-home prices in Gurugram have risen sharply.
06What could go wrong
- Property cycle. Housing demand can fall quickly when rates rise.
- Concentration. Heavy dependence on one city.
- Execution. Delays hurt cash flow and reputation.
07What the full DLF valuation shows
Sign in free to see the complete DLF valuation
- ✓The full model workings — and exactly where the model and the market part ways
- ✓Every assumption — growth, returns and cost of capital, with sources
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against Lodha Developers, UltraTech Cement and Asian Paints
- ✓Downloadable report — the full write-up, yours to keep
08Compare DLF with peers
The same valuation, run side by side.
DLF vs LodhaThe two largest listed developers, on different regional books.→DLF vs UltraTech CementThe developer against the cement it builds with.→DLF vs Asian PaintsBoth ride the same home-building and renovation demand.→09Questions people ask about DLF
What is DLF Cyber City Developers?
DLF's rental joint venture with GIC, which owns offices and malls.
Why are real-estate companies hard to value?
Their value depends on land, future launches and sale prices that do not show in past profits.
DLF or Lodha — which is better value?
The two largest listed developers, compared side by side on their own page.
Is DLF overvalued?
At ₹759 the market is pricing in roughly 35% sustained growth, against the ~9% its own record supports. That is more than it has delivered, so the price is justified only if the business can hold a rate it has not previously sustained.
What is the intrinsic value of DLF?
This business is a group of operations with different economics, so a single blended figure would describe none of them. The parts are valued separately and the breakdown is in the report, rather than one number that cannot be defended.
How much debt does DLF carry?
Debt to equity stands at 0.00, down from 0.03 at the start of the period — the balance sheet is a core input to the cost of capital used here.