On this page ▾
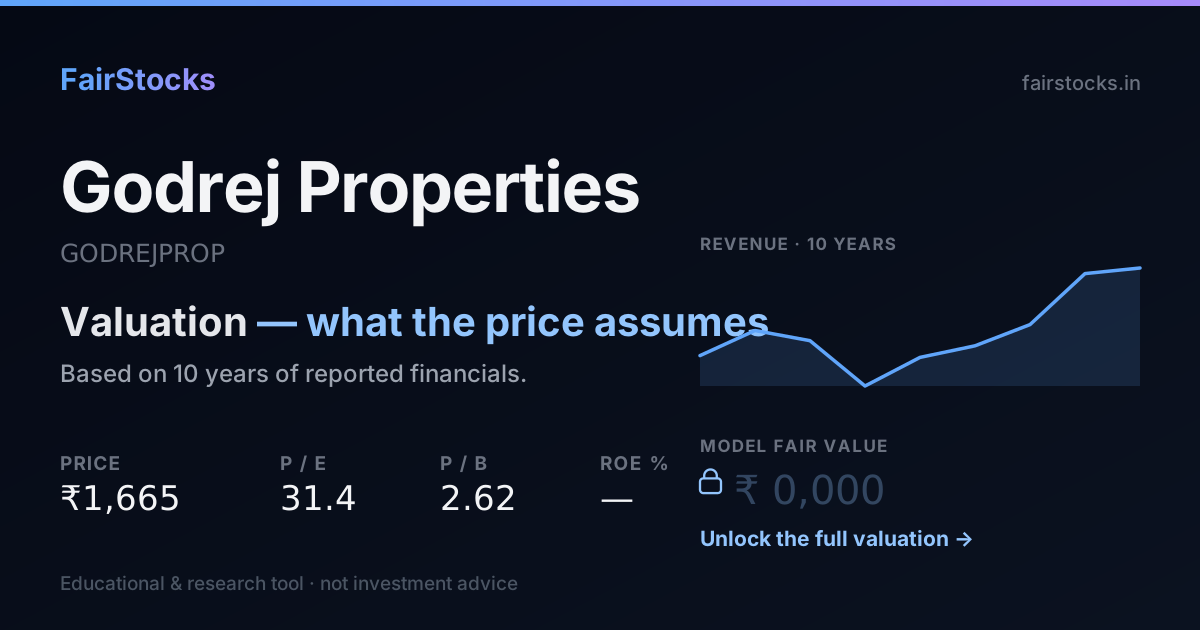
We do not publish one number for Godrej Properties — and here is why.
Our engine has not published a single fair value for Godrej Properties. A developer's worth lies in land and projects it will sell over many years, which its past cash flows describe poorly — especially while it is buying land heavily. The workings and the record are shown instead.
- How it is valued: business by business, with no single blended figure.
- What the price assumes: 35% growth, against 33% the model takes from its own record.
- Ten-year record: Between FY2018 and FY2026, Godrej Properties' revenue went from ₹1,889 crore to ₹5,131 crore — it compounded at about 13% a year over 8 years.
- Biggest swing factor: Bookings. Main risk: Property cycle.
01The Godrej group's homebuilder
Godrej Properties, part of the Godrej group, develops housing — and some offices — in Mumbai, Pune, the Delhi region, Bengaluru, Hyderabad and other cities. It became known for joint-development deals with landowners that needed little capital.
In recent years it has bought more land outright and raised equity to fund growth, and its annual bookings have risen to among the highest in the industry.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for Godrej Properties, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Godrej Properties' record, in plain numbers
Between FY2018 and FY2026, Godrej Properties' revenue went from ₹1,889 crore to ₹5,131 crore — it compounded at about 13% a year over 8 years. It reported a net loss in FY2021, and closed the period with net profit of ₹1,841 crore. In FY2026 it kept 35.9% of revenue as net profit — its best year in the period. The latest year added 4.2% to revenue, well behind its own long-run pace.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2018 | 1,889 | 235 | 12.4% |
| FY2019 | 2,817 | 253 | 9.0% |
| FY2020 | 2,441 | 271 | 11.1% |
| FY2021 | 765 | -189 | -24.8% |
| FY2022 | 1,825 | 351 | 19.2% |
| FY2023 | 2,252 | 621 | 27.6% |
| FY2024 | 3,036 | 747 | 24.6% |
| FY2025 | 4,923 | 1,389 | 28.2% |
| FY2026 | 5,131 | 1,841 | 35.9% |
04How Godrej Properties gets valued — and why
Estimate withheld — the engine says so itselfThis is a group of businesses with different economics. A single discounted cash flow across all of them averages them into something that describes none of them, so our engine withholds a single blended fair value rather than publishing a number it cannot defend. The parts are valued separately instead.
05What decides Godrej Properties' value
Bookings
Pre-sales drive future revenue and cash.
Land acquisition
New land supports launches but uses capital.
Margins
Project profitability determines value.
Brand
The Godrej name helps sell homes before they are built.
06What could go wrong
- Property cycle. Housing demand can fall with higher rates.
- Capital intensity. Buying land outright raises risk.
- Execution. Delays hurt cash flow.
07What the full Godrej Properties valuation shows
Sign in free to see the complete Godrej Properties valuation
- ✓The full model workings — and exactly where the model and the market part ways
- ✓Every assumption — growth, returns and cost of capital, with sources
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against DLF, Lodha and other developers
- ✓Downloadable report — the full write-up, yours to keep
08Questions people ask about Godrej Properties
Why is a developer hard to value?
Its value depends on land and future launches that do not appear in past profits.
How does Godrej Properties grow?
Through land purchases and joint developments with landowners.
Godrej Properties or DLF — which is better value?
Two large listed developers, compared on their own pages.
Is Godrej Properties overvalued?
At ₹1,855 the market is pricing in roughly 35% sustained growth, against the ~33% its own record supports. That is more than it has delivered, so the price is justified only if the business can hold a rate it has not previously sustained.
What is the intrinsic value of Godrej Properties?
This business is a group of operations with different economics, so a single blended figure would describe none of them. The parts are valued separately and the breakdown is in the report, rather than one number that cannot be defended.
How much debt does Godrej Properties carry?
Debt to equity stands at 0.12, against 0.00 at the start of the period — the balance sheet is a core input to the cost of capital used here.