On this page ▾
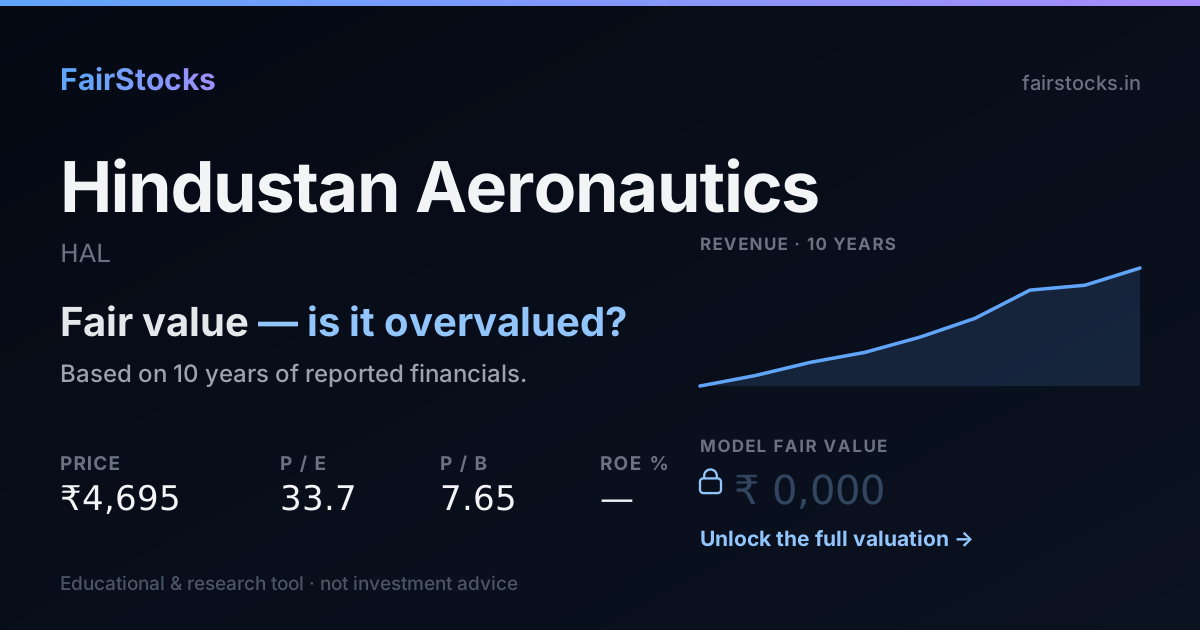
The market expects Hindustan Aeronautics to do better than it ever has.
At today’s share price, buyers are assuming Hindustan Aeronautics grows about 21% a year, forever. Over the last ten years it actually grew about 8% a year. So the share price only makes sense if the business improves on its own track record. If it simply carries on as before, buyers today have paid for something they will not get.
- How it is valued: Discounted cash flow.
- What the price assumes: 21% growth, against 8% the model takes from its own record.
- Ten-year record: Between FY2018 and FY2026, Hindustan Aeronautics' revenue went from ₹18,624 crore to ₹33,089 crore — it compounded at about 7% a year over 8 years.
- Biggest swing factor: Order book execution. Main risk: One customer.
01India's military aircraft maker
Hindustan Aeronautics (HAL) is a state-owned aerospace company based in Bengaluru and majority-owned by the Government of India. It builds the Tejas light combat aircraft, the Dhruv and Prachand helicopters and trainer aircraft, assembles the Su-30MKI under licence, and makes aero-engines and parts.
A large share of its revenue comes from repairing and overhauling the aircraft it has already delivered — steady, high-margin work. Its main customer is India's armed forces, and contracts are long, large and lumpy.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for Hindustan Aeronautics, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Hindustan Aeronautics' record, in plain numbers
Between FY2018 and FY2026, Hindustan Aeronautics' revenue went from ₹18,624 crore to ₹33,089 crore — it compounded at about 7% a year over 8 years. Net profit grew from ₹2,073 crore to ₹9,116 crore, about 20% a year — faster than revenue, so margins widened. In FY2026 it kept 27.5% of revenue as net profit — its best year in the period. The latest year added 6.8% to revenue, close to its own long-run pace.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2018 | 18,624 | 2,073 | 11.1% |
| FY2019 | 19,894 | 2,282 | 11.5% |
| FY2020 | 21,522 | 2,898 | 13.5% |
| FY2021 | 22,755 | 3,239 | 14.2% |
| FY2022 | 24,620 | 5,080 | 20.6% |
| FY2023 | 26,927 | 5,828 | 21.6% |
| FY2024 | 30,381 | 7,621 | 25.1% |
| FY2025 | 30,981 | 8,364 | 27.0% |
| FY2026 | 33,089 | 9,116 | 27.5% |
04How Hindustan Aeronautics gets valued — and why
Discounted cash flowThis business is valued on the cash it is expected to generate, discounted back at its cost of capital — with growth taken from its own ten-year record rather than from guidance.
05What decides Hindustan Aeronautics' value
Order book execution
HAL's revenue for years ahead is already ordered; how fast it delivers decides how fast earnings grow.
Engine supply
Tejas deliveries depend on imported engines, and supply delays have held them back.
Margins
Profit margins have risen strongly; whether they hold as new programmes ramp up is key.
Exports
Export orders would add a new source of growth beyond India's own budget.
06What could go wrong
- One customer. Almost all revenue depends on India's defence budget and procurement decisions.
- Programme delays. Development and supply-chain delays are common in aerospace.
- A high bar. When a share price assumes rapid growth, delays matter more.
07What the full HAL valuation shows
Sign in free to see the complete Hindustan Aeronautics valuation
- ✓Fair value per share — from a ten-year discounted cash flow, every step shown
- ✓The Workbench — change revenue growth, the discount rate or terminal growth and watch HAL's value move
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against Bharat Electronics, Larsen & Toubro and Adani Ports
- ✓Downloadable report — the full write-up, yours to keep
08Compare Hindustan Aeronautics with peers
The same valuation, run side by side.
Hindustan Aeronautics vs Larsen & ToubroDefence manufacturing against engineering and construction, both order-book led.→Hindustan Aeronautics vs Bharat ElectronicsThe nearest listed defence electronics comparison.→Hindustan Aeronautics vs Adani PortsTwo long-cycle asset businesses with government as the counterparty.→09Questions people ask about Hindustan Aeronautics
Why has HAL's profit grown so fast?
Mostly from higher margins on a growing base of manufacturing and repair work. The record paragraph on this page shows how profit grew relative to revenue.
Does HAL's order book guarantee growth?
It gives visibility on revenue, but timing depends on deliveries, engine supply and government payments.
HAL or Bharat Electronics — which is better value?
Both are state-owned defence companies valued on the same cash-flow model; the comparison page sets them side by side.
Is Hindustan Aeronautics overvalued?
At ₹4,810 the market is pricing in roughly 21% sustained growth, against the ~8% its own record supports. That is more than it has delivered, so the price is justified only if the business can hold a rate it has not previously sustained.
What is the intrinsic value of Hindustan Aeronautics?
It is computed from the filed financial statements using the method that fits this business (discounted cash flow), with every assumption shown alongside the result. The per-share figure and the full working are in the report.
How much debt does Hindustan Aeronautics carry?
Debt to equity stands at 0.00, against 0.00 at the start of the period — the balance sheet is a core input to the cost of capital used here.