On this page ▾
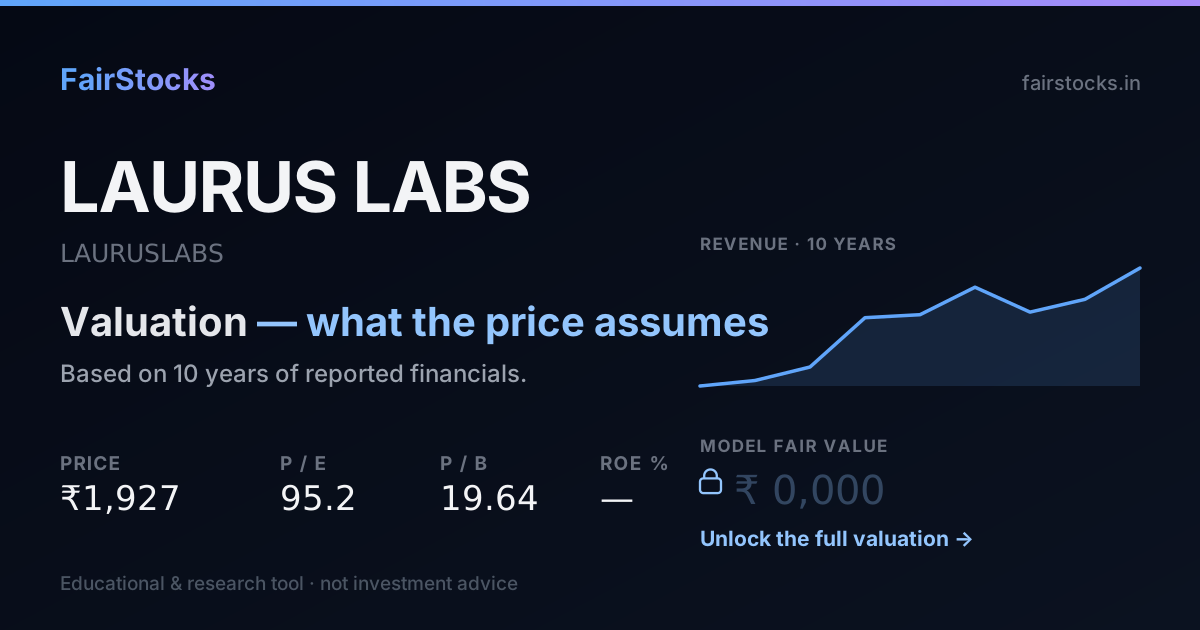
We do not publish one number for Laurus Labs — and here is why.
On today's figures the market pays roughly 3.9 times what our model says Laurus Labs is worth. On a company this widely followed, a gap that large almost always means our model is missing something rather than that thousands of investors are wrong. So we show the workings and say plainly that we cannot stand behind a single figure here.
- How it is valued: no single figure is published here — our model and the market disagree too far.
- What the price assumes: 35% growth, against 11% the model takes from its own record.
- Ten-year record: Between FY2018 and FY2026, Laurus Labs' revenue went from ₹2,069 crore to ₹6,813 crore — it compounded at about 16% a year over 8 years.
- Biggest swing factor: CDMO contracts. Main risk: Customer concentration.
01A Hyderabad API and CDMO company
Laurus Labs, founded in Hyderabad in 2005 by Dr Satyanarayana Chava, is a major maker of active pharmaceutical ingredients for antiretroviral (HIV) and other medicines, and of finished generic drugs.
Its contract development and manufacturing (CDMO) business makes ingredients for global pharmaceutical companies' patented drugs, and it is investing in biotech and cell and gene therapy capacity.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for Laurus Labs, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Laurus Labs' record, in plain numbers
Between FY2018 and FY2026, Laurus Labs' revenue went from ₹2,069 crore to ₹6,813 crore — it compounded at about 16% a year over 8 years. Net profit grew from ₹168 crore to ₹890 crore, about 23% a year — faster than revenue, so margins widened. In FY2026 it kept 13.1% of revenue as net profit — against a low of 3.2% in FY2024 and a high of 20.4% in FY2021. The latest year added 22.7% to revenue, well ahead of its own long-run pace.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2018 | 2,069 | 168 | 8.1% |
| FY2019 | 2,292 | 94 | 4.1% |
| FY2020 | 2,832 | 255 | 9.0% |
| FY2021 | 4,814 | 984 | 20.4% |
| FY2022 | 4,936 | 832 | 16.9% |
| FY2023 | 6,041 | 793 | 13.1% |
| FY2024 | 5,041 | 162 | 3.2% |
| FY2025 | 5,554 | 358 | 6.5% |
| FY2026 | 6,813 | 890 | 13.1% |
04How Laurus Labs gets valued — and why
Estimate withheld — model and market disagree too farOur model and the market disagree so far apart on this company that the model is the more likely one to be wrong. Rather than publish a number we cannot stand behind, we show the workings and say so.
05What decides Laurus Labs' value
CDMO contracts
Long-term work for innovators drives margins.
ARV pricing
HIV ingredient prices have fallen.
New capacity
Investment must be filled with orders.
Biotech
New platforms are long-term options.
06What could go wrong
- Customer concentration. A few large contracts matter a lot.
- Price erosion. Generic ingredient prices keep falling.
- The premium. The price assumes CDMO growth delivers.
07What the full Laurus Labs valuation shows
Sign in free to see the complete Laurus Labs valuation
- ✓The full model workings — and exactly where the model and the market part ways
- ✓Every assumption — growth, returns and cost of capital, with sources
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against Divi's Laboratories, Aurobindo Pharma and other drugmakers
- ✓Downloadable report — the full write-up, yours to keep
08Questions people ask about Laurus Labs
What does Laurus Labs make?
Ingredients and finished drugs for HIV and other diseases, plus contract manufacturing.
What is a CDMO?
A contract development and manufacturing organisation that makes drug ingredients for other companies.
Why did Laurus Labs' profit fall in FY2024?
Lower ARV prices and the end of some one-off contract work.
Is Laurus Labs overvalued?
At ₹2,424 the market is pricing in roughly 35% sustained growth, against the ~11% its own record supports. That is more than it has delivered, so the price is justified only if the business can hold a rate it has not previously sustained.
What is the intrinsic value of Laurus Labs?
This business is a group of operations with different economics, so a single blended figure would describe none of them. The parts are valued separately and the breakdown is in the report, rather than one number that cannot be defended.
How much debt does Laurus Labs carry?
Debt to equity stands at 0.12, down from 0.19 at the start of the period — the balance sheet is a core input to the cost of capital used here.