On this page ▾
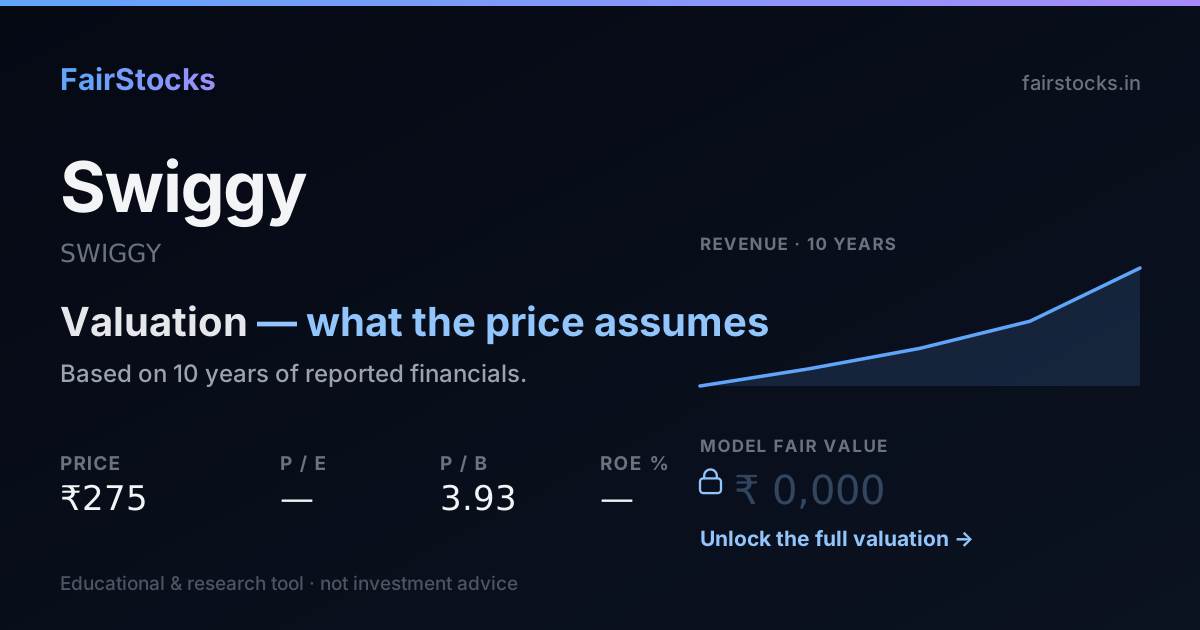
We do not publish one number for Swiggy — and here is why.
Swiggy is really several different businesses under one roof, and they do not work the same way. Adding them together into a single “fair value” would produce a figure that describes none of them. So we value each part on its own terms instead of printing one number that looks tidy and means little.
- How it is valued: business by business, with no single blended figure.
- What the price assumes: 35% growth, against 35% the model takes from its own record.
- Ten-year record: Between FY2022 and FY2026, Swiggy's revenue went from ₹5,705 crore to ₹23,053 crore — it compounded at about 42% a year over 4 years.
- Biggest swing factor: Food delivery profitability. Main risk: Price wars.
01Bengaluru's delivery platform
Swiggy, founded in Bengaluru in 2014 by Sriharsha Majety, Nandan Reddy and Rahul Jaimini, is one of India's two big food-delivery apps. It listed on the stock exchange in November 2024.
Instamart delivers groceries in minutes from dark stores, and the group also runs Dineout for restaurant bookings and events. Quick commerce is growing fast but losing money as it expands.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for Swiggy, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Swiggy's record, in plain numbers
Between FY2022 and FY2026, Swiggy's revenue went from ₹5,705 crore to ₹23,053 crore — it compounded at about 42% a year over 4 years. It reported a net loss in FY2022, FY2023, FY2024, FY2025 and FY2026. In FY2026 it lost the equivalent of 18.0% of revenue — its best year in the period. The latest year added 51.4% to revenue, well ahead of its own long-run pace.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2022 | 5,705 | -3,629 | -63.6% |
| FY2023 | 8,265 | -4,179 | -50.6% |
| FY2024 | 11,247 | -2,350 | -20.9% |
| FY2025 | 15,227 | -3,117 | -20.5% |
| FY2026 | 23,053 | -4,154 | -18.0% |
04How Swiggy gets valued — and why
Estimate withheld — the engine says so itselfThis is a group of businesses with different economics. A single discounted cash flow across all of them averages them into something that describes none of them, so our engine withholds a single blended fair value rather than publishing a number it cannot defend. The parts are valued separately instead.
05What decides Swiggy's value
Food delivery profitability
The core business needs rising margins.
Instamart losses
How fast quick commerce stops losing money.
Order growth
More users and orders spread fixed costs.
Competition
Eternal's Blinkit, Zepto and others are fighting hard.
06What could go wrong
- Price wars. Discounting delays profitability.
- Cash burn. Losses could require more capital.
- Regulation. Rules on gig workers or dark stores could raise costs.
07What the full Swiggy valuation shows
Sign in free to see the complete Swiggy valuation
- ✓The full model workings — and exactly where the model and the market part ways
- ✓Every assumption — growth, returns and cost of capital, with sources
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against Eternal and other internet platforms
- ✓Downloadable report — the full write-up, yours to keep
08Questions people ask about Swiggy
When did Swiggy list?
In November 2024.
What is Instamart?
Swiggy's quick-commerce service delivering groceries in minutes.
Is Swiggy profitable?
Food delivery is profitable at the operating level; the group still reports losses because of Instamart's expansion.
Is Swiggy overvalued?
At ₹191 the market is pricing in roughly 35% sustained growth, against the ~35% its own record supports. That is close to what it has delivered, so the price is broadly consistent with the company simply continuing as it has.
What is the intrinsic value of Swiggy?
This business is a group of operations with different economics, so a single blended figure would describe none of them. The parts are valued separately and the breakdown is in the report, rather than one number that cannot be defended.
How much debt does Swiggy carry?
Debt to equity stands at 0.00, against 0.00 at the start of the period — the balance sheet is a core input to the cost of capital used here.