On this page ▾
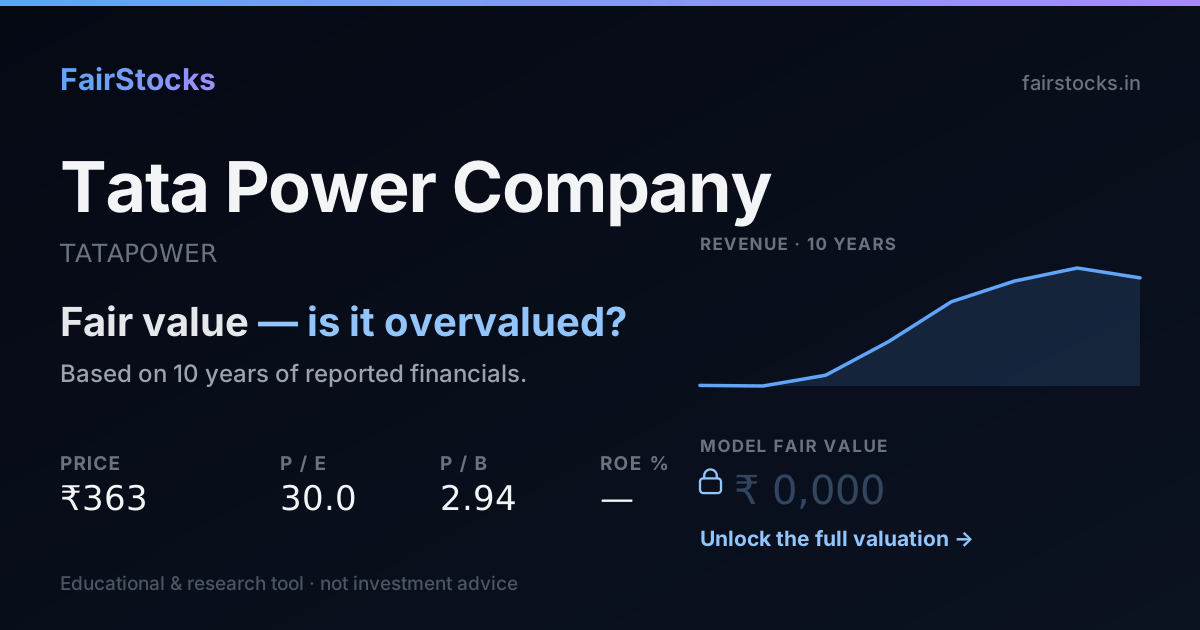
The market expects Tata Power to carry on much as it has.
At today’s share price, buyers are assuming Tata Power grows about 7% a year, forever. Over the last ten years it actually grew about 9% a year. The two are close, so the share price does not need the business to improve or to stumble. It needs it to keep doing roughly what it already does.
- How it is valued: Discounted cash flow.
- What the price assumes: 7% growth, against 9% the model takes from its own record.
- Ten-year record: Between FY2018 and FY2026, Tata Power's revenue went from ₹29,331 crore to ₹62,429 crore — it compounded at about 10% a year over 8 years.
- Biggest swing factor: Renewable capacity. Main risk: Execution.
01Generation, renewables and distribution
Tata Power, part of the Tata group, built India's first large hydro plants in the early 1900s. It generates power from coal, hydro and a fast-growing renewable portfolio, and distributes electricity in Mumbai, north Delhi and Odisha.
Through its renewables arm it develops solar and wind farms, makes solar cells and modules, installs rooftop solar and runs EV charging. Its Mundra coal plant has long been a drag on returns.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for Tata Power, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Tata Power's record, in plain numbers
Between FY2018 and FY2026, Tata Power's revenue went from ₹29,331 crore to ₹62,429 crore — it compounded at about 10% a year over 8 years. Net profit grew from ₹2,679 crore to ₹5,118 crore, about 8% a year — roughly in step with revenue. In FY2026 it kept 8.2% of revenue as net profit — against a low of 4.4% in FY2021 and a high of 9.1% in FY2018. Revenue slipped 4.7% in the latest year, well behind its own long-run pace. FY2019 is missing from the filed series used here, so that year is left out rather than estimated.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2018 | 29,331 | 2,679 | 9.1% |
| FY2020 | 29,136 | 1,316 | 4.5% |
| FY2021 | 32,468 | 1,439 | 4.4% |
| FY2022 | 42,816 | 2,156 | 5.0% |
| FY2023 | 55,109 | 3,810 | 6.9% |
| FY2024 | 61,449 | 4,280 | 7.0% |
| FY2025 | 65,478 | 4,775 | 7.3% |
| FY2026 | 62,429 | 5,118 | 8.2% |
04How Tata Power gets valued — and why
Discounted cash flowThis business is valued on the cash it is expected to generate, discounted back at its cost of capital — with growth taken from its own ten-year record rather than from guidance.
05What decides Tata Power's value
Renewable capacity
New solar and wind projects drive growth.
Solar manufacturing
Cell and module plants add a new profit stream.
Distribution
Regulated distribution earns steady returns.
Mundra
Tariff relief on the imported-coal plant affects profit.
06What could go wrong
- Execution. Large renewable pipelines can slip.
- Debt. Heavy capex raises borrowing.
- Regulation. Tariff decisions shape returns.
07What the full Tata Power valuation shows
Sign in free to see the complete Tata Power valuation
- ✓Fair value per share — from a ten-year discounted cash flow, every step shown
- ✓The Workbench — change revenue growth, the discount rate or terminal growth and watch Tata Power's value move
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against NTPC, Adani Green and other power companies
- ✓Downloadable report — the full write-up, yours to keep
08Questions people ask about Tata Power
What does Tata Power do?
It generates and distributes electricity, builds solar and wind farms, makes solar panels and runs rooftop solar and EV charging.
Where does Tata Power distribute electricity?
In Mumbai, north Delhi and Odisha.
What is the Mundra plant?
A large imported-coal power station that has weighed on Tata Power's returns.
Is Tata Power overvalued?
At ₹348 the market is pricing in roughly 7% sustained growth, against the ~9% its own record supports. That is less than it has delivered — on these numbers the market is asking the business for less than its own record, which usually means it doubts the record repeats.
What is the intrinsic value of Tata Power?
It is computed from the filed financial statements using the method that fits this business (discounted cash flow), with every assumption shown alongside the result. The per-share figure and the full working are in the report.
How much debt does Tata Power carry?
Debt to equity stands at 1.58, against 1.09 at the start of the period — the balance sheet is a core input to the cost of capital used here.