On this page ▾
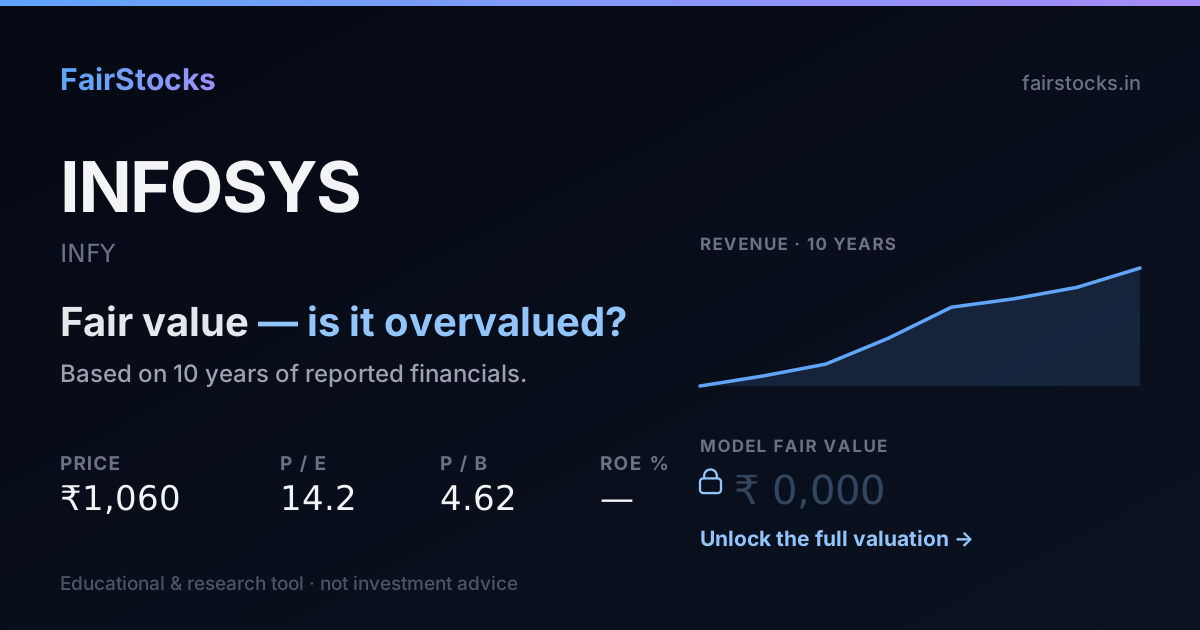
The market expects much less from Infosys than it has delivered before.
At today’s share price, buyers are assuming Infosys grows about 0% a year, forever. Over the last ten years it actually grew about 8% a year. That is a big step down from its own record — in other words, that it stops growing altogether. Either the market can see a problem that the published accounts do not show yet, or it is expecting a slowdown that has not happened.
- How it is valued: Discounted cash flow.
- What the price assumes: 0% growth, against 8% the model takes from its own record.
- Ten-year record: Between FY2019 and FY2026, Infosys' revenue went from ₹82,675 crore to ₹1,78,650 crore — it compounded at about 12% a year over 7 years.
- Biggest swing factor: Large deal wins. Main risk: Financial-services concentration.
01What Infosys sells, and to whom
Infosys, founded in Pune in 1981 by N. R. Narayana Murthy and six co-founders and now based in Bengaluru, is India's second-largest IT services company. It runs digital transformation, cloud, data and AI programmes for large companies, mainly in North America and Europe, and owns Finacle, a core-banking platform used by banks worldwide.
Like its peers, Infosys earns in foreign currency and pays most of its costs in rupees. The business is asset-light, so its value comes down to how fast revenue grows and how much of it becomes profit.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for Infosys, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Infosys' record, in plain numbers
Between FY2019 and FY2026, Infosys' revenue went from ₹82,675 crore to ₹1,78,650 crore — it compounded at about 12% a year over 7 years. Net profit grew from ₹15,410 crore to ₹29,474 crore, about 10% a year — slower than revenue, so margins narrowed. Net margin has been unusually stable, between 16.4% and 19.3% in every year shown. The latest year added 9.6% to revenue, close to its own long-run pace.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2019 | 82,675 | 15,410 | 18.6% |
| FY2020 | 90,791 | 16,639 | 18.3% |
| FY2021 | 1,00,472 | 19,423 | 19.3% |
| FY2022 | 1,21,641 | 22,146 | 18.2% |
| FY2023 | 1,46,767 | 24,108 | 16.4% |
| FY2024 | 1,53,670 | 26,248 | 17.1% |
| FY2025 | 1,62,990 | 26,750 | 16.4% |
| FY2026 | 1,78,650 | 29,474 | 16.5% |
04How Infosys gets valued — and why
Discounted cash flowThis business is valued on the cash it is expected to generate, discounted back at its cost of capital — with growth taken from its own ten-year record rather than from guidance.
05What decides Infosys' value
Large deal wins
Big multi-year contracts give visibility, but they often start at lower margins.
Operating margin
Wage increases and pricing pressure can push margins below the company's own target range.
Discretionary spending
Consulting and transformation projects are the first things clients cut when budgets tighten.
Capital return
Dividends and buybacks hand back most free cash flow, so shareholder value tracks cash generation closely.
06What could go wrong
- Financial-services concentration. Banks are its largest client group, so a banking slowdown hits Infosys first.
- AI deflation. Automation could shrink the hours clients pay for faster than new AI work replaces them.
- Currency. A stronger rupee lowers reported revenue and margins.
07What the full Infosys valuation shows
Sign in free to see the complete Infosys valuation
- ✓Fair value per share — from a ten-year discounted cash flow, every step shown
- ✓The Workbench — change revenue growth, the discount rate or terminal growth and watch Infosys' value move
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against TCS, HCLTech, Wipro and Sun Pharma
- ✓Downloadable report — the full write-up, yours to keep
08Compare Infosys with peers
The same valuation, run side by side.
Infosys vs Tata Consultancy ServicesThe two largest Indian IT services firms, on the same cash-flow model.→Infosys vs HCL TechnologiesComparable scale, a different services mix.→Infosys vs WiproThe nearest peer on size and client concentration.→Infosys vs Sun PharmaBoth earn most of their money in dollars and report it in rupees.→09Questions people ask about Infosys
Is Infosys cheaper than TCS?
On P/E Infosys has often traded below TCS. Whether that makes it better value depends on growth and margins, which the same cash-flow model tests for both; the Infosys vs TCS page sets them side by side.
Why does Infosys pay out so much of its profit?
Its business needs little capital, so most free cash flow is not needed for growth. Infosys has a stated policy of returning a large share of free cash flow through dividends and buybacks.
How could AI affect Infosys' valuation?
It cuts both ways: lower delivery costs can lift margins, but clients may push for lower prices. The Workbench in the full valuation lets you change the growth rate and see what it does to the value.
Is Infosys overvalued?
At ₹1,142 the market is pricing in roughly 0% sustained growth, against the ~8% its own record supports. That is less than it has delivered — on these numbers the market is asking the business for less than its own record, which usually means it doubts the record repeats.
What is the intrinsic value of Infosys?
It is computed from the filed financial statements using the method that fits this business (discounted cash flow), with every assumption shown alongside the result. The per-share figure and the full working are in the report.