On this page ▾
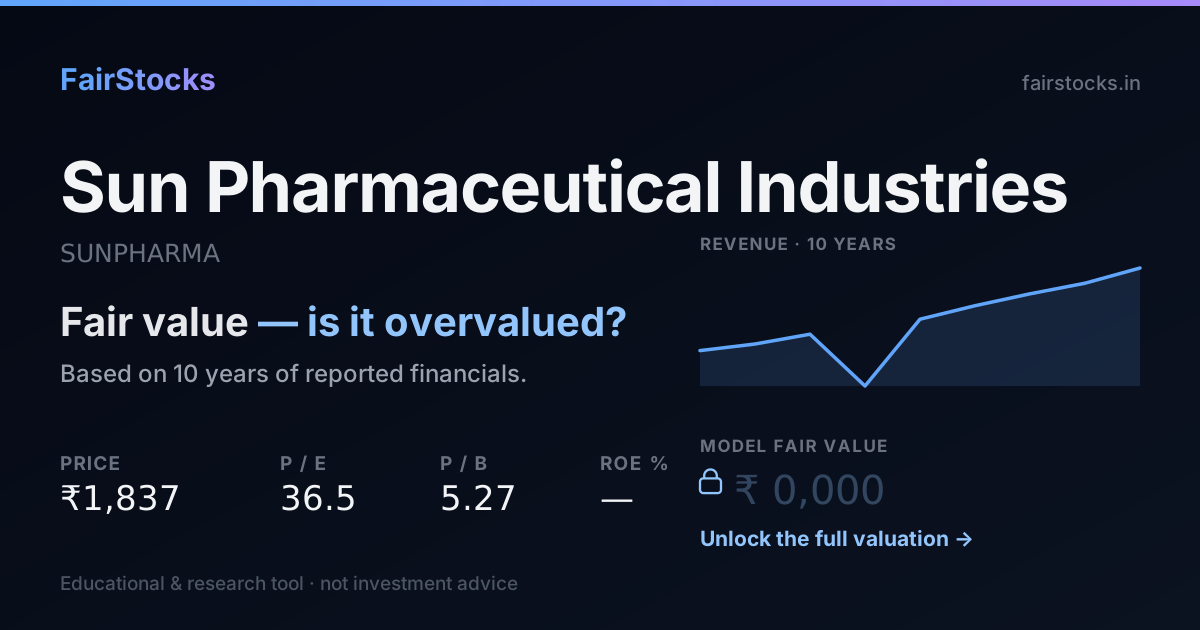
The market expects much less from Sun Pharma than it has delivered before.
At today’s share price, buyers are assuming Sun Pharma grows about 7% a year, forever. Over the last ten years it actually grew about 16% a year. That is a big step down from its own record. Either the market can see a problem that the published accounts do not show yet, or it is expecting a slowdown that has not happened.
- How it is valued: Discounted cash flow.
- What the price assumes: 7% growth, against 16% the model takes from its own record.
- Ten-year record: Between FY2018 and FY2026, Sun Pharma's revenue went from ₹26,489 crore to ₹58,462 crore — it compounded at about 10% a year over 8 years.
- Biggest swing factor: Specialty growth. Main risk: US FDA compliance.
01From generics to specialty medicines
Sun Pharmaceutical Industries, founded by Dilip Shanghvi in 1983, is India's largest pharmaceutical company and the leader in branded prescriptions in India. It sells generics in the US, emerging markets and Europe, and owns Taro Pharmaceutical, a dermatology-focused generics maker it took fully private in 2024.
Over the past decade it has built a global specialty business — patented drugs such as Ilumya for psoriasis, along with dermatology and eye-care brands — which earn far higher margins than generics and are less exposed to price erosion.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for Sun Pharma, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Sun Pharma's record, in plain numbers
Between FY2018 and FY2026, Sun Pharma's revenue went from ₹26,489 crore to ₹58,462 crore — it compounded at about 10% a year over 8 years. Net profit grew from ₹2,608 crore to ₹11,509 crore, about 20% a year — faster than revenue, so margins widened. In FY2026 it kept 19.7% of revenue as net profit — against a low of 8.8% in FY2022 and a high of 20.9% in FY2025. The latest year added 11.2% to revenue, close to its own long-run pace. FY2021 is missing from the filed series used here, so that year is left out rather than estimated.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2018 | 26,489 | 2,608 | 9.8% |
| FY2019 | 29,066 | 3,208 | 11.0% |
| FY2020 | 32,838 | 4,172 | 12.7% |
| FY2021 | 12,803 | 2,140 | 16.7% |
| FY2022 | 38,654 | 3,389 | 8.8% |
| FY2023 | 43,886 | 8,513 | 19.4% |
| FY2024 | 48,497 | 9,610 | 19.8% |
| FY2025 | 52,578 | 10,965 | 20.9% |
| FY2026 | 58,462 | 11,509 | 19.7% |
04How Sun Pharma gets valued — and why
Discounted cash flowThis business is valued on the cash it is expected to generate, discounted back at its cost of capital — with growth taken from its own ten-year record rather than from guidance.
05What decides Sun Pharma's value
Specialty growth
The specialty portfolio is the main reason Sun earns a higher multiple than most Indian pharma companies. Its growth rate drives the valuation.
The India business
Branded prescriptions in India are steady, cash-rich and grow with the domestic market.
US generic pricing
Prices for older generics keep falling as buyers consolidate; new launches have to offset that erosion.
R&D spend
Developing specialty drugs depresses margins today in exchange for revenue later.
06What could go wrong
- US FDA compliance. Warning letters or import alerts at a manufacturing site can block US sales from that plant for years.
- Trial and patent risk. A failed trial or an early generic challenge can wipe out expected specialty revenue.
- US policy. Tariffs on imported medicines and drug-pricing reforms could change US economics.
07What the full Sun Pharma valuation shows
Sign in free to see the complete Sun Pharma valuation
- ✓Fair value per share — from a ten-year discounted cash flow, every step shown
- ✓The Workbench — change revenue growth, the discount rate or terminal growth and watch Sun Pharma's value move
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against Dr Reddy's, Cipla and Divi's Laboratories
- ✓Downloadable report — the full write-up, yours to keep
08Compare Sun Pharma with peers
The same valuation, run side by side.
Sun Pharma vs Dr Reddy'sBoth large-cap pharma with substantial US generics exposure.→Sun Pharma vs CiplaA more India-and-emerging-markets weighted book.→Sun Pharma vs Divi's LaboratoriesContract manufacturing rather than branded generics.→Sun Pharma vs InfosysBoth earn most of their money in dollars and report it in rupees.→Sun Pharma vs Hindustan UnileverTwo defensive businesses — one sells medicine, the other soap — put through the same durability test.→09Questions people ask about Sun Pharma
Why does Sun Pharma trade at a higher P/E than other Indian drugmakers?
Largely because of its specialty portfolio, which earns higher margins and faces less price erosion than generics. The DCF tests how much of that premium the cash flows support.
How important is the US market to Sun Pharma?
Very. The US is where both its generics and its specialty drugs earn most, so FDA inspections, pricing and trade policy there move the whole company.
Is Sun Pharma a defensive stock?
Medicines are bought whatever the economy does, so demand is steadier than in most sectors. The risks are regulatory and pricing-related instead of cyclical.
Is Sun Pharma overvalued?
At ₹1,880 the market is pricing in roughly 7% sustained growth, against the ~16% its own record supports. That is less than it has delivered — on these numbers the market is asking the business for less than its own record, which usually means it doubts the record repeats.
What is the intrinsic value of Sun Pharma?
It is computed from the filed financial statements using the method that fits this business (discounted cash flow), with every assumption shown alongside the result. The per-share figure and the full working are in the report.
How much debt does Sun Pharma carry?
Debt to equity stands at 0.00, against 0.00 at the start of the period — the balance sheet is a core input to the cost of capital used here.