On this page ▾
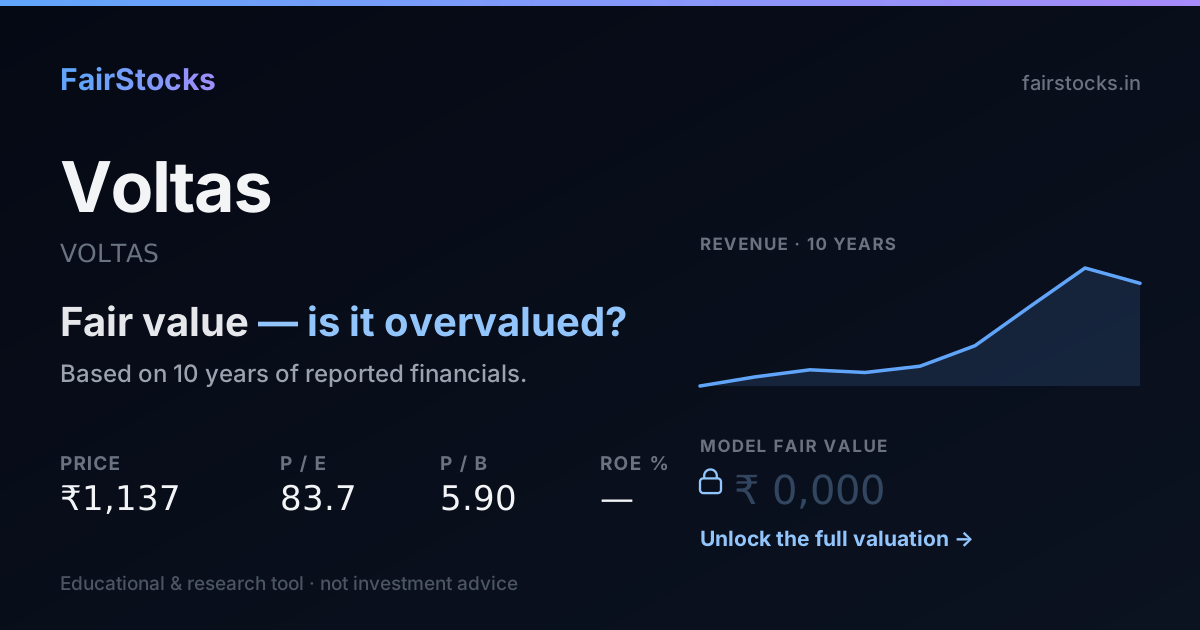
The market expects much less from Voltas than it has delivered before.
At today’s share price, buyers are assuming Voltas grows about 14% a year, forever. Over the last ten years it actually grew about 18% a year. That is a big step down from its own record. Either the market can see a problem that the published accounts do not show yet, or it is expecting a slowdown that has not happened.
- How it is valued: Discounted cash flow.
- What the price assumes: 14% growth, against 18% the model takes from its own record.
- Ten-year record: Between FY2018 and FY2026, Voltas' revenue went from ₹6,428 crore to ₹14,244 crore — it compounded at about 10% a year over 8 years.
- Biggest swing factor: Summer heat. Main risk: Mild summers.
01The Tata group's cooling company
Voltas, part of the Tata group, leads India's room air-conditioner market and sells air coolers, commercial refrigeration and, through Voltbek — a joint venture with Turkey's Arçelik — refrigerators and washing machines.
It also runs an engineering projects business in India and the Middle East, building electrical, plumbing and HVAC systems for buildings and infrastructure.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for Voltas, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03Voltas' record, in plain numbers
Between FY2018 and FY2026, Voltas' revenue went from ₹6,428 crore to ₹14,244 crore — it compounded at about 10% a year over 8 years. Net profit fell from ₹578 crore to ₹370 crore, about 5% a year — slower than revenue, so margins narrowed. In FY2026 it kept 2.6% of revenue as net profit — against a low of 1.4% in FY2023 and a high of 9.0% in FY2018. Revenue slipped 7.6% in the latest year, well behind its own long-run pace.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2018 | 6,428 | 578 | 9.0% |
| FY2019 | 7,124 | 514 | 7.2% |
| FY2020 | 7,658 | 521 | 6.8% |
| FY2021 | 7,457 | 529 | 7.1% |
| FY2022 | 7,934 | 506 | 6.4% |
| FY2023 | 9,499 | 136 | 1.4% |
| FY2024 | 12,481 | 248 | 2.0% |
| FY2025 | 15,413 | 834 | 5.4% |
| FY2026 | 14,244 | 370 | 2.6% |
04How Voltas gets valued — and why
Discounted cash flowThis business is valued on the cash it is expected to generate, discounted back at its cost of capital — with growth taken from its own ten-year record rather than from guidance.
05What decides Voltas' value
Summer heat
Hot summers drive AC demand.
AC penetration
Low ownership leaves room to grow.
Voltbek
Appliances add growth.
Projects margins
Avoiding losses in projects.
06What could go wrong
- Mild summers. Cool weather cuts sales.
- Competition. LG, Daikin, Blue Star and others.
- Project losses. Overseas projects have hurt profit.
07What the full Voltas valuation shows
Sign in free to see the complete Voltas valuation
- ✓Fair value per share — from a ten-year discounted cash flow, every step shown
- ✓The Workbench — change revenue growth, the discount rate or terminal growth and watch Voltas' value move
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against Havells, Blue Star and other appliance makers
- ✓Downloadable report — the full write-up, yours to keep
08Questions people ask about Voltas
What does Voltas sell?
Room ACs, air coolers, commercial refrigeration and, through Voltbek, appliances.
What is Voltbek?
Voltas' appliance joint venture with Turkey's Arçelik.
Why do summers matter to Voltas?
Most AC sales happen in hot months.
Is Voltas overvalued?
At ₹1,153 the market is pricing in roughly 14% sustained growth, against the ~18% its own record supports. That is less than it has delivered — on these numbers the market is asking the business for less than its own record, which usually means it doubts the record repeats.
What is the intrinsic value of Voltas?
It is computed from the filed financial statements using the method that fits this business (discounted cash flow), with every assumption shown alongside the result. The per-share figure and the full working are in the report.
How much debt does Voltas carry?
Debt to equity stands at 0.06, against 0.00 at the start of the period — the balance sheet is a core input to the cost of capital used here.