On this page ▾
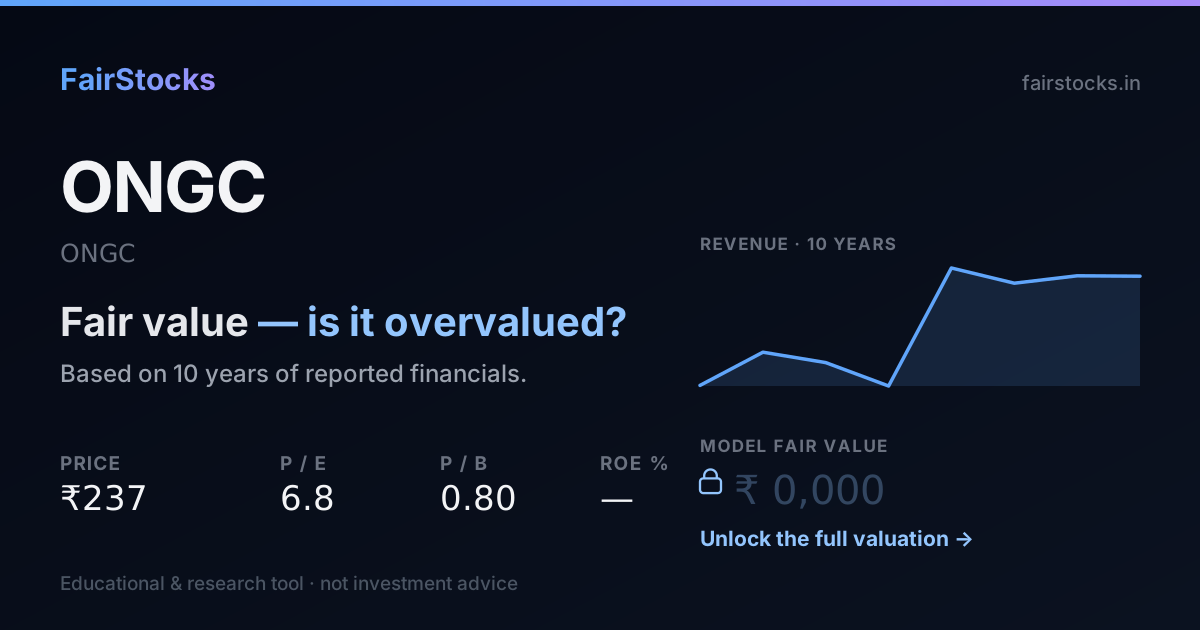
The market expects Oil and Natural Gas Corporation to carry on much as it has.
At today’s share price, buyers are assuming Oil and Natural Gas Corporation grows about 0% a year, forever. Over the last ten years it actually grew about 0% a year. The two are close, so the share price does not need the business to improve or to stumble. It needs it to keep doing roughly what it already does.
- How it is valued: Discounted cash flow.
- What the price assumes: 0% growth, against 0% the model takes from its own record.
- Ten-year record: Between FY2018 and FY2026, ONGC's revenue went from ₹3,62,246 crore to ₹6,62,247 crore — it compounded at about 8% a year over 8 years.
- Biggest swing factor: Crude oil prices. Main risk: Government intervention.
01India's oil and gas producer — and a refiner too
Oil and Natural Gas Corporation is India's largest producer of crude oil and natural gas, majority-owned by the Government of India. Its overseas arm, ONGC Videsh, holds oil and gas assets in other countries.
ONGC also owns a majority of Hindustan Petroleum (HPCL) and Mangalore Refinery and Petrochemicals (MRPL). Their refining and fuel sales make up most of ONGC's consolidated revenue, so the revenue line is much bigger than the oil-and-gas business at its core.
02What the market is assuming
Work backwards from today's share price and you can see what buyers are quietly taking for granted. Here is the growth that price implies for ONGC, next to what the model assumes from the company's own record.
The further apart these two numbers are, the bigger the bet a buyer at today's price is making.
03ONGC's record, in plain numbers
Between FY2018 and FY2026, ONGC's revenue went from ₹3,62,246 crore to ₹6,62,247 crore — it compounded at about 8% a year over 8 years. Net profit grew from ₹26,068 crore to ₹49,793 crore, about 8% a year — roughly in step with revenue. In FY2026 it kept 7.5% of revenue as net profit — against a low of 2.7% in FY2020 and a high of 8.9% in FY2024. Revenue slipped 0.2% in the latest year, well behind its own long-run pace. FY2022 is missing from the filed series used here, so that year is left out rather than estimated.
Revenue and earnings per share in ₹, return on equity and leverage as ratios — all from the filed statements.
Revenue and net profit by year (₹ crore)
| Year | Revenue | Net profit | Margin |
|---|---|---|---|
| FY2018 | 3,62,246 | 26,068 | 7.2% |
| FY2019 | 4,53,461 | 33,887 | 7.5% |
| FY2020 | 4,25,001 | 11,560 | 2.7% |
| FY2021 | 3,60,572 | 21,343 | 5.9% |
| FY2023 | 6,84,829 | 32,778 | 4.8% |
| FY2024 | 6,43,037 | 57,101 | 8.9% |
| FY2025 | 6,63,262 | 38,329 | 5.8% |
| FY2026 | 6,62,247 | 49,793 | 7.5% |
04How ONGC gets valued — and why
Discounted cash flowThis business is valued on the cash it is expected to generate, discounted back at its cost of capital — with growth taken from its own ten-year record rather than from guidance.
05What decides ONGC's value
Crude oil prices
Higher prices lift ONGC's realisations, though government levies have capped the gains in the past.
Production volumes
Many fields are mature; new deep-water projects need to offset natural decline.
Gas pricing
Domestic gas prices are set by a government formula with a floor and a ceiling.
HPCL's marketing margins
Fuel retail margins depend on how far retail prices are allowed to track costs.
06What could go wrong
- Government intervention. Windfall taxes and pricing controls have taken away upside before.
- Field decline. Without new discoveries, output falls year after year.
- Energy transition. Long-term demand for oil may fall.
07What the full ONGC valuation shows
Sign in free to see the complete ONGC valuation
- ✓Fair value per share — from a ten-year discounted cash flow, every step shown
- ✓The Workbench — change revenue growth, the discount rate or terminal growth and watch ONGC's value move
- ✓Bull, base and bear cases — and exactly which assumptions move between them
- ✓Peer comparison — against Reliance Industries, Indian Oil and NTPC
- ✓Downloadable report — the full write-up, yours to keep
08Compare ONGC with peers
The same valuation, run side by side.
ONGC vs Reliance IndustriesUpstream production against refining plus consumer — opposite ends of the same barrel.→ONGC vs NTPCBoth state-controlled energy, on very different regulatory footing.→ONGC vs Indian OilRefining and marketing rather than exploration.→09Questions people ask about ONGC
Why is ONGC's revenue so large?
Because it consolidates HPCL and MRPL, whose refining and fuel sales dwarf ONGC's own oil and gas revenue.
How do oil prices affect ONGC?
Higher crude prices raise ONGC's realisations but squeeze HPCL's refining and marketing margins, so the group is partly hedged.
ONGC or Reliance — which is better value?
They are compared side by side on their own page; one is upstream production and the other refining plus consumer businesses.
Is ONGC overvalued?
At ₹225 the market is pricing in roughly 0% sustained growth, against the ~0% its own record supports. That is close to what it has delivered, so the price is broadly consistent with the company simply continuing as it has.
What is the intrinsic value of ONGC?
It is computed from the filed financial statements using the method that fits this business (discounted cash flow), with every assumption shown alongside the result. The per-share figure and the full working are in the report.
How much debt does ONGC carry?
Debt to equity stands at 0.30, down from 0.36 at the start of the period — the balance sheet is a core input to the cost of capital used here.